

He Always Handled the Money. Now What?
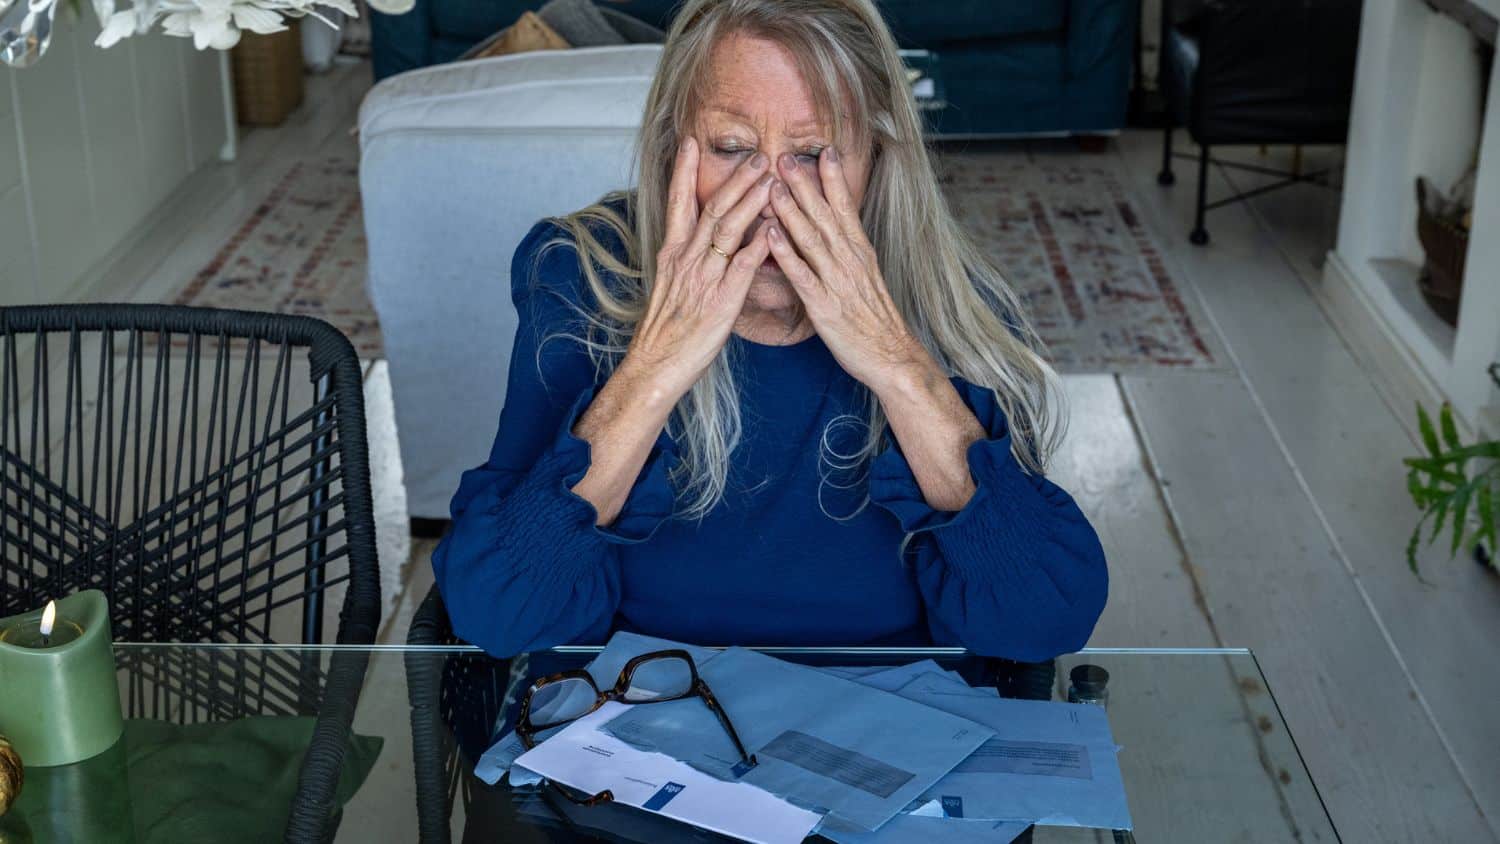
Theresa is 72 years old, and she’s sitting at her kitchen table staring at a bill she doesn’t understand.
It’s not an especially complicated bill. At least, she doesn’t think it is. It’s something to do with the homeowners insurance, and there’s a notice about a change in coverage that she isn’t quite sure how to interpret.
Her husband would have known what to do with it.
For 46 years, he handled most of their finances. He paid the bills, dealt with insurance, monitored their investments, and knew which accounts held what. Theresa handled plenty of other things. Between them, they had built a household, raised children, navigated careers, cared for aging parents, and managed all the ordinary complications of a life together.
Their arrangement worked.
Until it didn’t.
Now her husband is gone, and Theresa finds herself confronting not only the enormous absence he left behind, but also a collection of responsibilities she never expected to handle alone.
She looks at the insurance notice again.
How can I be 72 years old and not know how to do this?
And just like that, an unfamiliar piece of paperwork becomes evidence of something much bigger.
Maybe she’s not good with money. Maybe she never was. Maybe she’s simply too old to learn.
But there’s another possibility worth considering.
Maybe Theresa isn’t bad with money. Maybe she’s just new at this.
When a Division of Labor Becomes an Identity
Long relationships tend to develop divisions of labor.
One person cooks. The other handles the yard. One remembers everyone’s birthdays. The other keeps the cars running. One manages the household finances while the other handles the dozens of logistical and emotional responsibilities that keep a family functioning.
Sometimes these arrangements are negotiated deliberately. More often, they evolve over time.
Someone has a little more experience with a task, so they take it on. Then they get better at it through repetition, which makes it increasingly sensible for them to continue doing it.
Eventually, the arrangement becomes so familiar that nobody thinks much about it.
And there’s nothing inherently wrong with that.
But something interesting can happen when we start confusing the responsibilities we’ve assumed with the abilities we possess.
“He handles the money” gradually becomes “He’s the one who’s good with money.”
And sometimes, without anyone explicitly saying it, that becomes “I’m not good with money.”
Those statements aren’t equivalent.
Theresa wasn’t incapable of managing the finances. She simply hadn’t been the person doing it.
She had spent decades coordinating family schedules, navigating complicated medical decisions, managing household needs, and solving problems that required patience, judgment, organization, and persistence.
Nobody questioned her competence in those areas.
Yet when she encountered an unfamiliar insurance statement, she questioned her competence as a person.
That’s an awfully harsh conclusion to draw from a single piece of paper.
Grief Makes Learning Harder
There’s another important part of Theresa’s situation that conventional financial advice sometimes overlooks.
She’s grieving.
And grief doesn’t politely stay in the emotional parts of our lives.
It can affect concentration, memory, motivation, sleep, and our ability to make decisions. Things that once seemed manageable can suddenly require tremendous effort.
Now imagine trying to learn an entirely unfamiliar financial system while experiencing all of that.
You call the insurance company and struggle to follow the explanation. You read the same paragraph three times. You forget a question you meant to ask. You put off opening another envelope because you simply don’t have the energy.
It’s easy to interpret those experiences as evidence that you’re incapable.
But difficulty concentrating while grieving doesn’t mean you lack intelligence. Feeling overwhelmed by unfamiliar information doesn’t mean you can’t learn it.
And needing help doesn’t mean you’ve failed.
There’s an enormous difference between saying, I don’t understand this, and saying, I can’t understand this.
The first describes your current experience. The second makes a prediction about your future.
And sometimes there’s a third possibility:
I might be able to understand this, but today may not be the day.
Of course, some financial matters have deadlines and consequences that can’t be ignored. Insurance coverage, estate administration, benefits, and potential fraud may require timely attention, even when you’re exhausted.
But recognizing that something needs attention doesn’t mean you have to figure it out entirely by yourself.
The Invisible Financial Curriculum
Think about something you’ve done regularly for decades.
Maybe you’ve coordinated medical appointments for your family. Maybe you’ve managed a complicated household calendar, maintained a garden, or organized family gatherings involving relatives who don’t particularly like one another.
You probably know things about those activities that you don’t even realize you know.
You know what to anticipate, which details matter, whom to call when something goes wrong, and which problems can wait.
You didn’t acquire that knowledge in a single afternoon.
You learned it through experience.
Financial management works much the same way.
Someone who has paid the homeowners insurance for 30 years knows roughly when the renewal arrives. They recognize the company’s name. They know what the policy usually costs and whether a change deserves investigation.
Someone encountering that same paperwork for the first time doesn’t have those reference points.
That isn’t a difference in intelligence. It’s just a difference in experience.
And unfortunately, the financial world isn’t particularly welcoming to beginners.
Statements arrive filled with terminology that assumes you already understand it. Websites present options without explaining their consequences. Professionals sometimes move quickly through explanations that make perfect sense to them but leave you wondering whether you’re supposed to know what they’re talking about.
It can feel like walking into a class halfway through the semester.
Everyone else seems to understand the material. You’re still trying to figure out what the abbreviations mean.
And because money is so closely tied to ideas about responsibility, independence, and competence, asking a basic question can feel embarrassing.
But unfamiliarity isn’t incompetence.
It’s unfamiliarity.
That’s all.
The Pressure to Become Independent Overnight
After the death of a spouse, friends and family often offer advice with the best of intentions.
“You need to take control of your finances.”
“Make sure nobody takes advantage of you.”
“You really need to understand where everything is.”
Those concerns may be entirely reasonable.
But to someone who is grieving and already feeling overwhelmed, they can sound like an assignment to become a financial expert immediately.
Suddenly, you’re supposed to understand investments, insurance, taxes, retirement distributions, estate documents, and every account your spouse spent decades managing.
And preferably by Thursday.
There’s a distinction I wish we made more often between financial autonomy and doing everything yourself.
Autonomy means having meaningful input into decisions that affect your life. It means understanding your options well enough to make informed choices, having access to information, and retaining authority over your own circumstances.
It doesn’t mean you have to become your own accountant, investment manager, attorney, and insurance specialist.
In fact, knowing when to ask for help is often part of making good, future-focused decisions.
The important question isn’t whether you can do everything independently. It’s whether the people helping you are supporting your ability to make decisions or quietly taking those decisions away from you.
A good professional should be willing to explain things in language you understand. They should welcome questions. They should be able to tell you what requires attention now, what can wait, and what the consequences of different choices might be.
And you should never have to pretend you understand something simply to avoid feeling embarrassed.
A Gentler Way to Begin
When someone is facing an unfamiliar financial situation, I often find it helpful to make the task smaller.
Not because the person is incapable of handling something complicated, but because complicated things become more manageable when we stop demanding that we understand all of them at once.
Instead of asking, “How am I going to manage all of this?” try starting with three questions.
What Actually Needs My Attention Right Now?
Not everything unfamiliar is urgent.
Some things genuinely require prompt action, such as maintaining insurance coverage, responding to certain legal notices, or addressing suspicious activity on an account.
Other decisions may be able to wait until you have more information, more support, or simply more capacity.
If you don’t know which is which, identifying that distinction is a perfectly reasonable first task.
What Do I Need to Understand Well Enough to Make the Next Decision?
You don’t necessarily need to understand every detail of an insurance policy to find out whether your coverage is about to lapse.
You don’t need to become an investment expert to ask a financial advisor to explain how an account works.
And you don’t need to master an entire financial system to take one useful step within it.
The goal isn’t to know everything.
It’s to know enough to decide what happens next.
Who Can Help Me Understand This Without Taking the Decision Away from Me?
This question matters enormously.
A trusted family member may be able to help organize paperwork. An attorney may be needed for estate matters. A financial advisor may help explain investments, while a financial coach can help with learning, decision-making, and building confidence.
The right support depends on the situation.
But whatever kind of help you seek, notice how the person responds to your questions.
Do they slow down when you’re confused? Do they explain the alternatives? Do they respect your preferences? Do you leave the conversation understanding more than when you arrived? Or do you feel pressured to agree because they seem to know more than you?
Getting help should increase your understanding and choices, not diminish them.
And when someone is newly bereaved, it can be particularly important to have trustworthy support around decisions that are difficult to reverse.
Sometimes the Paperwork Isn’t Just Paperwork
One afternoon, Theresa finds a handwritten note tucked into an insurance folder.
It’s her husband’s handwriting.
Nothing sentimental. Just a phone number, a policy renewal date, and a reminder to ask about a discount.
For a moment, she can almost hear him explaining it. And then she remembers that she can’t ask him.
This is something I think we overlook when we talk about managing money after the loss of a spouse.
The financial tasks themselves may not be the hardest part.
Every unfamiliar account can be another reminder that someone is missing. Every question you can’t ask can reopen the grief. Every responsibility you take over can make the loss feel a little more permanent.
And sometimes there’s frustration mixed into that grief.
Theresa loved her husband. She appreciated the way he took care of their finances. She knows he wasn’t trying to leave her unprepared.
But she also wishes she’d paid more attention. She wishes they’d talked more about where everything was.
And, if she’s being particularly candid, she’s a little irritated that she now has to learn all of this when she’s already dealing with so much.
That frustration doesn’t diminish her love for him. It doesn’t mean their arrangement was wrong. It means she’s a human being experiencing several difficult things at once.
Grief and gratitude can coexist. So can love and resentment.
And none of those feelings makes her less capable of learning what she needs to know.
Becoming a Beginner Isn’t Starting Over
Although Theresa’s story begins with widowhood, the experience of suddenly becoming responsible for unfamiliar financial decisions isn’t limited to losing a spouse.
Perhaps you’re recently divorced after a long marriage.
Perhaps your partner is experiencing cognitive decline, and responsibilities that once belonged to them are gradually becoming yours.
Perhaps you spent years in a relationship where financial decisions were controlled by someone else.
Or maybe nothing dramatic has happened at all. You’ve simply reached a point in your life where you’d like to understand your finances better.
Whatever brought you here, there’s something important to remember.
You may be new to managing the money. You are not new to managing life.
You have decades of experience making decisions, solving problems, adapting to circumstances, and learning things you once didn’t know how to do.
You may have navigated career changes, family crises, illnesses, moves, losses, and unexpected challenges.
Those experiences don’t automatically teach you how a retirement account works. But they do tell something about your capacity to learn, adapt, and make thoughtful decisions. And that capacity doesn’t disappear simply because you’ve reached a particular birthday.
One of the unfortunate things about the way we talk about aging is that we sometimes treat learning as something that belongs to younger people.
At 25, not knowing something means you’re inexperienced.
At 72, we can start treating that same unfamiliarity as though it’s evidence of decline.
But age doesn’t magically provide experience in tasks you’ve never performed. Nor does it disqualify you from learning them. You are allowed to encounter something new at 65, 75, or 85 without turning it into a judgment about yourself.
Theresa’s Next Bill
Theresa doesn’t become a financial expert overnight. She doesn’t suddenly develop a passion for insurance policies or retirement account statements. But she does something different the next time an unfamiliar notice arrives.
Instead of staring at it and wondering what is wrong with her, she writes down what she doesn’t understand. She calls the insurance company. When the representative uses a term she doesn’t recognize, she asks what it means. And when the explanation still doesn’t make sense, she asks again.
The conversation takes longer than she expected. She doesn’t learn everything. But she understands what the notice is about, what her options are, and what she needs to do next.
That’s enough for today.
Not because she’s lowered her expectations for herself, but because she’s stopped confusing learning with already knowing.
Closing Thoughts
If you’re facing financial responsibilities you’ve never handled before, you may feel frightened, frustrated, embarrassed, or overwhelmed.
You may miss the person who used to take care of these things.
You may wish you’d learned more years ago.
You may even find yourself feeling angry that you have to learn them now.
All of those experiences can make sense.
But none of them is evidence that you’re incapable.
Financial confidence isn’t something you’re required to possess before you begin. Often, it’s something that develops through the experience of asking questions, making decisions, getting help, and discovering that you can learn.
You don’t have to know everything about money to begin making decisions about it.
You don’t have to become an expert overnight.
And you don’t have to apologize for being a beginner.
You’ve spent a lifetime learning how to live. You’re allowed to keep learning.
Let’s Have a Conversation:
At what age did you learn how to manage your finances? Was it a gradual process? Who did you call to ask questions when you didn’t understand something? Do you presently manage your finances? What insecurities have you faced in this regard?